Lowcountry Real Estate, Mortgage, & Homeownership Resources

Welcome to the Rainbow Row Real Estate blog—practical, locally focused information for buying, selling, financing and owning a home along the South Carolina coast.

Here you’ll find straightforward explanations of the real estate and mortgage process, local market updates, neighborhood insights, homeowner resources and the occasional guide to Lowcountry life. Our goal is to help you make informed decisions without the pressure or confusing industry jargon.

Have a question or a topic you’d like us to cover? Reach out anytime. We’re always happy to have a local, no-pressure conversation.

Oct. 19, 2026

Mortgage Rates Enter a Quieter Week After Hot Inflation

Charleston Lowcountry marsh at sunrise with Mortgage Rate Watch and A Quieter Week After Hot Inflation headline

Mortgage Rate Watch | October 19–23, 2026

Mortgage rates begin a relatively quiet economic week near their highest level in almost three years. The lighter calendar may reduce the number of obvious market-moving moments, but the inflation concerns driving longer-term interest rates have not disappeared.

The Quick Take

Mortgage rates may appear quiet, but inflation reports can move them quickly. Instead of trying to time the market perfectly, buyers can start by understanding their payment range and available loan options.

Check Your Buying Power

Last week’s reports showed consumer and producer prices rising sharply in September. This week’s housing reports, unemployment claims and business surveys will help show whether those higher prices and borrowing costs are beginning to slow the economy.

Where Mortgage Rates Stand

Freddie Mac’s latest national survey put the average 30-year fixed mortgage rate at 7.40% as of October 15, unchanged from the previous week. The average 15-year fixed rate declined slightly to 6.71%.

These are national survey averages rather than individual rate quotes. A borrower’s actual rate depends on credit, down payment, property type, occupancy, loan program, discount points and other factors.

The 10-year Treasury yield was near 5.09% Monday morning. That is below the multiyear highs reached earlier in October, but still elevated enough to keep pressure on mortgage pricing.

Hot Inflation Is Still the Main Story

September’s Consumer Price Index rose 0.6% for the month and 3.7% from a year earlier. Core CPI, which removes food and energy, increased 0.3% for the month and 2.6% annually.

The following day, the Producer Price Index jumped 1.3%—its largest monthly increase since March 2022—and rose 6.3% over the year. Higher energy costs played a major role, but price pressure also appeared across services and other categories.

Those reports make the Federal Reserve’s job more difficult. The Fed raised its benchmark rate to 3.75%–4.00% in September and will announce its next decision on October 28.

Markets currently expect the Fed to pause next week, but another increase later in the year remains possible if inflation stays elevated.

Monday and Tuesday: Housing Takes the Lead

Monday’s NAHB Housing Market Index will provide an updated look at builder confidence, buyer traffic and sales expectations. The index is expected to decline slightly from 32 to 31.

Tuesday brings September Housing Starts and Pending Home Sales. Housing starts are expected to remain near an annualized pace of 1.3 million, while pending sales are forecast to decline approximately 0.3%.

These reports matter because housing is particularly sensitive to interest rates. Weaker construction and contract activity would show that elevated borrowing costs are cooling demand, although housing data alone may not produce a major change in mortgage pricing.

Thursday: Another Look at the Labor Market

Initial Jobless Claims are expected near 200,000, compared with 199,000 the previous week.

Monthly job growth slowed significantly in September, but weekly claims remain low. That combination suggests employers have become more cautious about hiring without broadly moving toward layoffs.

A meaningful increase in claims would strengthen the case that the labor market is cooling. Another low reading would allow the Fed to remain focused on inflation.

Friday: Business Costs and Inflation Expectations

Friday brings the first broad look at October business activity through S&P Global’s manufacturing and services surveys.

Both indexes are expected to remain comfortably above 50, indicating continued expansion. Markets will pay particular attention to comments about input costs, prices charged to customers, hiring and new business.

The final University of Michigan Consumer Sentiment survey follows at 10 a.m. Its measures of household inflation expectations may be more important for rates than the headline confidence reading.

If businesses and consumers increasingly expect prices to remain elevated, the Fed may find it harder to justify lower rates. Signs that cost pressures and inflation expectations are easing would be more encouraging for the bond market.

Jared’s Take

Mortgage rates held steady last week, but that does not mean the inflation problem has been resolved. The 10-year Treasury yield has moved off its recent high, which is helpful, but lasting rate improvement will probably require more convincing evidence that price pressures are cooling. This week may be quieter, but Friday’s reports can still change the market’s expectations heading into next week’s Fed meeting.

If you are buying or considering a refinance, the goal should not be to guess the lowest possible rate. It should be to understand your payment, options and rate-lock strategy before the market forces a rushed decision.

Start Your Pre-Approval

Let us know if you have any questions.

SOURCES

Oct. 17, 2026

Why We Participate in Pride: Everyone Deserves to Belong

Why We Participate in Pride: Everyone Deserves to Belong

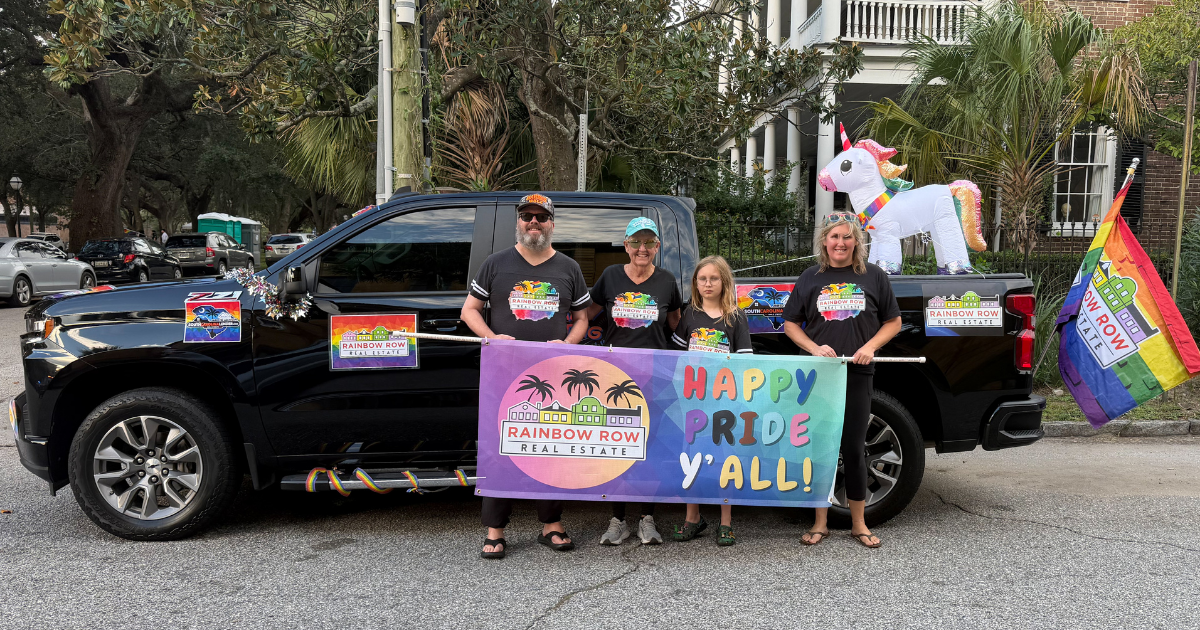
Today, we participated in the Charleston Pride Parade for the fifth straight year, representing Rainbow Row Real Estate and South Carolina Lender.

There’s a simple reason we keep showing up: We want people to know they are loved, accepted, and welcome exactly as they are.

We see it, too

We see the comments. We read the posts. We notice the dirty looks and hear people speak with cruelty about neighbors they may never have taken the time to know.

We also think about the person on the receiving end. The person reading those comments quietly. The kid wondering whether it’s safe to be themselves. The adult who still feels the need to hide part of their life to keep the peace.

That’s why we participate in Pride.

We know what it feels like to be different and to be bullied for who you are. Our experiences aren’t identical to anyone else’s, but they have taught us something worth carrying forward: Nobody should have to become someone else to deserve kindness and respect.

Acceptance should be something you can see

It’s easy to assume people already know they’re welcome. Sometimes, though, they need to hear it. Sometimes they need to see someone stand up, show up, and say it without hesitation.

So here it is:

We love and accept you as you are.

You deserve friendship, opportunity, happiness, and a place where you feel at home. You deserve to talk about the people you love without first wondering how someone will react.

For us, participating in Pride is one way to make that welcome visible.

These values come with us to work

We’re representing our businesses because our values come with us wherever we go.

Real estate and lending bring us into people’s lives during some pretty big moments. We hear about their families, their plans, their worries, and what they hope comes next.

That takes trust. We want the people who work with us to feel comfortable being themselves and confident they’ll be treated with care and respect.

A sense of belonging matters in a community. It matters on your street, in your neighborhood, and when you walk through your own front door.

Why we’ll keep showing up

We can’t control every hateful comment. We can’t change every mind during a parade.

But we can choose how we treat people. We can speak up when someone is being pushed aside. We can stand beside our neighbors and make sure they know they have support.

We’ll always choose love over hate, acceptance over exclusion, and happiness over hostility.

That’s why we participate in Pride.

And that’s why we’ll keep showing up.


Our Takeaway

You don’t have to understand every part of someone’s experience to treat them with kindness. You can listen, make room, and let them know they belong.

To our LGBTQ+ friends, family, clients, and neighbors: We’re glad you’re part of our community. You are welcome with us, exactly as you are.

—Jared & Erin
Rainbow Row Real Estate | South Carolina Lender

Let’s Find Your Place to Call Home

Posted in Lowcountry Living
Oct. 16, 2026

Lowcountry Real Estate Report: October 9–16, 2026

Lowcountry 7-Day Real Estate Report for October 9–16, 2026, covering Charleston, Berkeley, Dorchester and Colleton counties.

The Lowcountry 7-Day Real Estate Report: October 9–16, 2026

New inventory remained almost perfectly level across the Lowcountry this week, while closings increased and homes that reached the closing table spent less time on the market. Buyer activity eased slightly, but 272 homes still went under contract across the four-county region.

This report covers residential properties for sale in Charleston, Berkeley, Dorchester and Colleton counties. Rentals are not included.

Our Takeaway

The Lowcountry market continues to move at a steady pace. New inventory was virtually unchanged, closings increased and the average market time for sold homes improved. Buyers have choices, but well-positioned homes are still finding buyers.

This Week’s Lowcountry Real Estate Numbers

🟩 ↑ 469 new listings — up 1 from the previous report
🟩 ↑ 234 homes closed — up 40
🟥 ↓ 272 homes went under contract — down 8
🟥 ↓ 630 price changes — down 38
🟥 ↓ $865,994 average sold price — down $11,273
🟥 ↓ 51 average days on market — down 6 days

The arrows show whether each figure increased or decreased from the previous published report. They are directional indicators, not automatic judgments about whether a change is good or bad.

New Inventory Was Almost Completely Flat

The MLS added 469 new residential listings during the reporting period—just one more than the previous report. Charleston County contributed 226 new listings, Berkeley County added 134, Dorchester County added 98 and Colleton County added 11.

That kind of consistency gives us a useful picture of the current market. Buyers continue to receive a steady supply of new choices without seeing a sudden flood of inventory. There is more time to compare homes than there was during the unusually competitive pandemic market, but buyers should not assume that every appealing property will sit indefinitely.

For sellers, stable inventory means new competition continues to arrive every week. A listing must compare favorably with similar homes in price, condition, presentation and location.

Closings Increased

A total of 234 homes closed this week, an increase of 40 from the previous report. Charleston County led with 120 closings, followed by Berkeley County with 81, Dorchester County with 28 and Colleton County with five.

Closings reflect contracts negotiated several weeks earlier, so this increase tells us that buyers were actively making decisions and completing transactions during the late-summer and early-fall market.

Homes that closed this week spent an average of 51 days on the market, six days fewer than the previous report. That does not mean every home will sell within 51 days. Market time varies considerably based on neighborhood, price range, property type, condition and whether the home was positioned correctly from the beginning.

Buyer Activity Remained Steady

There were 272 homes placed under contract, eight fewer than the previous report. That is a relatively small week-to-week change and does not suggest that buyers have disappeared.

Charleston County recorded 114 new contracts, Berkeley County recorded 85, Dorchester County recorded 67 and Colleton County recorded six.

Buyers have more leverage than they did a few years ago, particularly when a property has been sitting on the market or needs updating. That leverage can include price negotiations, closing-cost assistance, repair requests or financing strategies such as a seller-paid temporary rate buydown.

Price Changes Remain an Important Signal

The MLS recorded 630 price changes this week. That was 38 fewer than the previous report, but it remains a significant amount of activity.

Charleston County recorded 238 price changes, Berkeley County had 227, Dorchester County had 143 and Colleton County had 22.

A price change does not automatically mean a seller made a mistake. New competing listings may enter the market, buyer feedback may reveal resistance at a particular price point or a seller’s priorities may change. What matters is recognizing what the market is saying and responding before the listing becomes stale.

Understanding the Average Sold Price

The average sold price was $865,994, down $11,273 from the previous report. This weekly movement should not be interpreted as a comparable decrease in Lowcountry property values.

Weekly averages are highly influenced by the specific combination of homes that close. A few luxury, waterfront or downtown transactions can move the average substantially in either direction. Neighborhood-level comparable sales and longer-term trends provide a much better measure of an individual property’s value.

Where Were the Most Closings?

  1. Summerville/Ladson in Berkeley County — 32 closings
  2. Mount Pleasant north of the Isle of Palms Connector — 21 closings
  3. Summerville/Ridgeville — 13 closings

County-by-County Breakdown

Charleston County
226 new listings
120 homes closed
114 went under contract
238 price changes

Berkeley County
134 new listings
81 homes closed
85 went under contract
227 price changes

Dorchester County
98 new listings
28 homes closed
67 went under contract
143 price changes

Colleton County
11 new listings
5 homes closed
6 went under contract
22 price changes

Our Take

New inventory was virtually unchanged, but closings increased and homes that sold spent less time on the market. Buyers are still moving, while 630 price changes remind sellers that price and presentation continue to matter.

For buyers, this market provides more opportunity to compare homes and negotiate thoughtfully. For sellers, success depends on understanding the competition and responding to buyer feedback before valuable market time is lost.

National headlines may provide context, but your neighborhood, property type and price range determine your real options. Local numbers and relevant comparable sales should guide the conversation.

Source: Charleston Regional MLS/FlexMLS. Activity from October 9, 2026, at 8:19 a.m. through October 16, 2026, at 8:19 a.m. Residential properties for sale only; rentals excluded.

Posted in Market Updates
Oct. 16, 2026

Our Lowcountry Fall Bucket List: 10 Ways to Make Family Memories

Our Lowcountry Fall Bucket List: 10 Ways to Make Family Memories

There's something special about fall in the Lowcountry.

The humidity finally starts backing off, football is in full swing, the mosquitoes become slightly less aggressive, and weekends suddenly fill up with pumpkin patches, corn mazes, festivals, and road trips.

Every year our family tries to get out and enjoy as much of October as we can. Whether you've lived here for years or just moved to the Charleston area, here are ten ideas to add to your family's fall bucket list.

Before heading out, check each destination's current schedule, ticket information, and weather updates. Farm activities and seasonal events can change.

1. Boone Hall Pumpkin Patch & Corn Maze

Mount Pleasant

Pumpkins, a corn maze, and a day of family fun make Boone Hall a classic Lowcountry fall outing. Give yourself enough time to explore instead of treating it as a quick stop for a pumpkin.

Jared's tip: Aim for an early visit and leave some breathing room in the day's schedule.

Check Boone Hall's pumpkin patch information

2. West Farm Corn Maze

1542 Cooper Store Road, Moncks Corner, SC 29461

West Farm offers a corn maze, hayrides, a farm zoo, and a play area with plenty to keep the kids busy. Make this a farm day rather than just a race to find the maze exit.

Jared's tip: Wear comfortable shoes you don't mind getting dusty, and bring your sense of humor if your family's navigation skills are anything like ours.

Plan your West Farm visit

3. Legare Farms

2620 Hanscombe Point Road, Johns Island, SC 29455

Legare Farms is part of the area's agricultural history and a familiar name in Lowcountry fall traditions. Check with the farm for this season's fall festival offerings and available farm products before planning your outing.

Jared's tip: See what locally grown or farm-made items are available to bring home. The outing might inspire dinner, too.

Check Legare Farms' latest information

4. Full Circle Farm

3014 River Road, Johns Island, SC 29455

For a farm outing on Johns Island, add Full Circle Farm to your list. Its farm experiences offer an opportunity to slow down and enjoy a different side of the Charleston area. Ask about available tours and seasonal activities before visiting.

Jared's tip: Bring the camera, but leave time to enjoy the visit between pictures.

Explore Full Circle Farm

5. Coastal Carolina Fair

Exchange Park, 9850 Highway 78, Ladson, SC 29456

Rides, games, exhibits, entertainment, and enough fried food to make your cardiologist nervous. The Coastal Carolina Fair is one of those traditions that can make the whole family feel like kids again.

Jared's tip: Consider a weekday outing if your schedule allows, and decide on your must-do rides and snacks before arriving.

Check fair dates, tickets, and entertainment

6. Bee City Zoo

1066 Holly Ridge Lane, Cottageville, SC 29435

Make an animal-filled day trip to Bee City Zoo, where interactive experiences offer plenty to explore. It's a fun option when you want to mix something different into your fall weekends.

Jared's tip: Check the zoo's event calendar separately if you're hoping to visit for an evening celebration. Its Christmas Festival of Lights is a later-season outing to keep on your radar.

Plan a Bee City Zoo outing

7. A Halloween Road Trip to Conway

Downtown Conway, South Carolina

This one takes you beyond the Charleston area, but Conway's October Halloween transformation makes a great excuse for a road trip. Explore the decorated downtown, browse local shops, and build in time for a walk along the riverfront.

Jared's tip: Bring your camera and pick a few things to do before leaving. A little planning helps make the longer drive worthwhile.

Explore Conway's Halloween festivities

8. Pick a Pumpkin and Make an Afternoon of It

You don't need a giant festival to create a fall tradition. Pick up pumpkins from a local seasonal stand, then head home for an afternoon of carving or painting.

Let everyone choose their own design. Add a few snacks, put on a favorite movie, and see whose pumpkin ends up with the most personality.

Jared's tip: Smaller outings can create some of the biggest family memories. Leave room on the calendar for something simple.

9. Take the Scenic Route

Take Highway 174 toward Edisto. Cruise Highway 17 toward Awendaw and McClellanville. Explore the back roads through Hollywood or Meggett.

We don't need mountain-style fall foliage to enjoy an October drive. Marsh views, oak trees, and a little less hurry are a pretty good combination.

Jared's tip: If you spot a roadside produce stand or a little restaurant you've never tried, make a stop. Those spontaneous detours can become the best part of the day.

10. Spend a Saturday Outside

A youth football game. A college football tailgate. A local farmers market. A walk in the park. A backyard evening with friends.

Fall weekends don't have to be expensive or packed with activities to become memorable. Sometimes the best plan is simply spending time together outside.

Jared's tip: Put the phone down for an hour and enjoy being there. October has a way of disappearing before we've made time for it.

Our Takeaway

One of my favorite things about living here is that every family has its own fall traditions. Some involve a full day on the road. Others happen right in the backyard.

Pick a couple of things your family will enjoy, get them on the calendar, and leave room for a few unplanned stops along the way.

What's one thing your family does every October that should be on everyone else's bucket list? If you received our fall bucket list email, hit reply and share it. I'd love to put together a Part 2 featuring your ideas.

Have a wonderful fall!

Posted in Lowcountry Living
Oct. 14, 2026

Inflation Came In Hotter Than Expected: What It Means for Mortgage Rates

Inflation Came In Hotter Than Expected: What It Means for Mortgage Rates

If you’ve been waiting for mortgage rates to drop, this morning’s inflation report probably wasn’t the news you wanted.

The September Consumer Price Index report, released October 14, showed inflation picking up. That matters because inflation is one of the factors influencing mortgage rates—and higher inflation can make borrowing more expensive.

But before you let another headline put your home search on hold, let’s walk through what the numbers mean.

What did the inflation report show?

According to the U.S. Bureau of Labor Statistics:

  • Overall consumer prices rose 3.7% over the past year, compared with 3.4% in August.

  • Prices increased 0.6% during September, following a 0.4% increase in August.

  • Core inflation, which excludes food and energy, reached 2.6% annually, up from 2.4% in August.

Gasoline was the biggest driver of the monthly increase. Prices jumped 9.1%, accounting for more than half of September’s overall rise. Shelter costs also increased 0.4%.

In plain English: inflation moved in the wrong direction, and the increase wasn’t limited to the gas pump.

Why does inflation affect mortgage rates?

Mortgage rates are closely connected to the bond market.

Investors buying bonds and mortgage-backed securities consider how inflation could reduce the purchasing power of their future earnings. When inflation concerns increase, investors may demand higher returns. That can translate into higher mortgage rates.

The Federal Reserve also influences financial conditions, but it doesn’t directly set the rate on your 30-year fixed mortgage. Mortgage pricing can change before a Fed meeting as investors react to economic reports and expectations.

Our read on today’s report: it creates upward pressure on mortgage rates rather than giving us a reason to expect immediate relief.

Does this mean rates will keep going up?

One report cannot tell us that.

Inflation, employment, economic growth, and investor expectations all play a role. The next round of data could reinforce today’s concerns or give the market a reason to settle down.

That’s why we’re cautious about anyone promising a particular mortgage rate by a particular date. There are too many moving pieces to build your homebuying plan around a prediction.

What should Charleston homebuyers do?

Start with a payment you can comfortably afford using the financing available today.

That means looking beyond the interest rate and considering:

  • The purchase price and down payment.

  • Property taxes, homeowners insurance, and any flood insurance.

  • Mortgage insurance and HOA fees, when applicable.

  • Closing costs and the savings you’ll have left afterward.

Depending on the property, loan program, and seller, there may also be opportunities to negotiate closing-cost assistance or explore a rate buydown. Those options deserve a comparison of the costs and benefits.

If you’re already under contract, talk with your lender about your closing timeline and rate-lock options. A lock decision should fit your transaction and your tolerance for payment changes.

What about waiting for lower rates?

Waiting may be the right choice if you need to build savings, improve credit, or get your budget into a better position.

But waiting solely for a lower rate has tradeoffs. If rates fall and more buyers enter the market, competition could increase and sellers may become less flexible. That outcome isn’t guaranteed, but it belongs in the conversation.

And if you buy now, make sure the payment works now. Refinancing later may be possible, but it comes with costs and qualification requirements. It shouldn’t be what makes an otherwise uncomfortable payment affordable.

Our Takeaway

You don’t have to predict the economy to make a sound homebuying decision.

You need to understand your payment, protect your savings, and decide whether the home fits your life and budget.

Today’s inflation report is useful information. It doesn’t have to make the decision for you.

Explore Your Homebuying Options

If you’re considering a home in Charleston, North Charleston, Summerville, or the surrounding Lowcountry, let’s look at the numbers together and build a plan around your situation.

Explore Your Homebuying Options

Sources: U.S. Bureau of Labor Statistics, September 2026 CPI report and Federal Reserve Bank of St. Louis, What Determines Mortgage Rates?.

Oct. 14, 2026

Things I Wish I Knew Earlier in Real Estate: The Contract Is Just the Beginning

Things I Wish I Knew Earlier in Real Estate: The Contract Is Just the Beginning

Welcome to Part 2 of Things I Wish I Knew Earlier in Real Estate, a series of lessons I've picked up over the years that I probably would have appreciated knowing a little sooner.

Today's lesson?

Getting a sales contract signed is the easiest part.

Now, before anyone thinks I'm dismissing the work that goes into finding the right home, marketing a listing, negotiating an offer, or getting everyone to agree on terms, I'm not.

Those things matter. A lot.

But a signed contract isn't the finish line.

In many ways, it's the starting line.

Congratulations! You're Under Contract!

For a buyer, it's exciting. You've found the house, negotiated the deal, and the seller has accepted your offer.

For a seller, it's a relief. The showings, cleaning, scheduling, and uncertainty have finally produced a buyer.

Everyone's happy.

And then the real work begins.

The Inspection Period

Home inspections can reveal issues nobody knew existed.

Sometimes they're minor. Sometimes they're expensive. And sometimes they require buyers and sellers to revisit negotiations they thought were already finished.

A good agent needs to understand the contract, keep track of deadlines, communicate clearly, and help clients evaluate their options.

It's not always about getting everything you ask for.

Sometimes it's about finding a reasonable solution that keeps the transaction moving while protecting your client's interests.

The Appraisal

Just because a buyer and seller agree on a price doesn't mean the appraiser will arrive at the same number.

What happens if the appraisal comes in low?

Depending on the contract and financing, the parties may need to renegotiate, bring additional funds to closing, challenge an appraisal with appropriate supporting information, or consider other options.

These aren't conversations you want to be figuring out for the first time while everyone is already stressed.

The Financing

A pre-approval is an important first step, but it isn't a guarantee that a mortgage will close.

Underwriting can uncover documentation questions, changes in financial circumstances, property-related concerns, or other conditions that need to be addressed.

And sometimes buyers unintentionally make things harder by opening new credit accounts, financing a vehicle, or changing jobs during the transaction.

This is why communication between the buyer, agent, and lender matters so much.

Having worked on both the real estate and mortgage sides of the business, I've developed an even greater appreciation for how much coordination goes into getting a transaction across the finish line.

Insurance, Title, and Everything Else

Insurance availability and cost can be significant factors here in the Lowcountry.

Then there's title work, survey questions, HOA documentation, closing attorney coordination, and all those little details that don't seem particularly exciting until something goes wrong.

Real estate has a funny way of reminding you that the smallest overlooked detail can create the biggest headache.

The Emotional Side of the Transaction

Here's something that doesn't get discussed enough.

Buyers and sellers are human.

They're making enormous financial decisions, coordinating moves, dealing with families, and often trying to manage all of this while working full-time jobs.

When something unexpected happens, emotions can take over.

Part of our job is to remain calm, explain what's happening, present realistic options, and help people make decisions without adding unnecessary drama.

Sometimes that means solving a problem.

Sometimes it means knowing who to call.

And sometimes it means having one of those uncomfortable conversations we talked about in Part 1.

See how these lessons start connecting?

Our Takeaway

A signed contract is a milestone. A successful closing is the goal.

I used to think the hardest part of real estate was getting someone to sign on the dotted line.

Over time, I've realized that the real value of experience shows up in everything that happens afterward.

The unexpected problems. The deadlines. The negotiations. The communication. The ability to keep everyone focused on the bigger picture.

A good transaction doesn't necessarily mean nothing went wrong.

Sometimes it means plenty went wrong, but the right people worked together to get it resolved.

And that's a lesson I wish I'd understood a little earlier.

Start Your Home Search


Buying or selling a home in the Charleston area? At Rainbow Row Real Estate, we're here to help you navigate the entire process, not just get a contract signed.

Connect with Rainbow Row Real Estate

Oct. 14, 2026

Things I Wish I Knew Earlier in Real Estate: Have the Uncomfortable Conversation

Things I Wish I Knew Earlier in Real Estate: Have the Uncomfortable Conversation

After more than a decade in real estate, I've learned a few things I wish someone had explained to me when I first got started.

Some lessons come from training. Some come from great mentors. And some come from making mistakes, dealing with difficult situations, and realizing afterward that there was probably a better way to handle things.

This is the first in a little series I'm calling Things I Wish I Knew Earlier in Real Estate.

And we're starting with a big one.

Have the Uncomfortable Conversation Early

Because I promise you, it's going to be REALLY uncomfortable later.

Nobody particularly enjoys delivering bad news. And when you're helping someone make one of the biggest financial decisions of their life, emotions can run pretty high.

It's natural to want everyone to be happy. But sometimes keeping everyone happy today creates a much bigger problem tomorrow.

The Pricing Conversation

Let's say a homeowner believes their property is worth $450,000, but the comparable sales suggest something closer to $410,000.

It's tempting to soften that conversation, especially when you're competing for a listing.

But what happens when the home sits on the market? Showings slow down. Price reductions follow. Frustration builds.

Now you're having the same conversation 60 days later, except the seller is disappointed, the listing has accumulated days on market, and you've lost valuable time.

Wouldn't it have been better to have that honest conversation on day one?

The Buyer Budget Conversation

Maybe a buyer has their heart set on a particular neighborhood or price range.

But after looking at the numbers, their comfortable monthly payment doesn't support that dream home.

That's not a fun conversation.

But it's a whole lot better than watching someone fall in love with a property they can't comfortably afford, or worse, stretching their finances beyond what makes sense for their family.

Sometimes the best thing we can do is help someone adjust the plan before they become emotionally invested.

The Little Problems That Become Big Problems

Inspection concerns. Repair expectations. Financing challenges. Unrealistic timelines.

Real estate transactions have plenty of opportunities for small misunderstandings to become major headaches.

And the longer those issues go unaddressed, the harder they can be to resolve.

A five-minute uncomfortable conversation today might prevent five days of stress next week.

Our Takeaway

You can be kind, respectful, compassionate, and still tell someone something they don't want to hear.

Those things aren't mutually exclusive.

I've learned that clients don't need someone who agrees with everything they say. They need someone willing to give them honest information, explain their options, and help them make informed decisions.

That's what being a professional is supposed to mean.

And if I could give my younger real estate self one piece of advice?

Have the conversation.

You'll be glad you did.

Let's Talk Real Estate


Thinking about buying or selling in the Charleston area? We'd love to have an honest conversation about your goals, your options, and what makes sense for you. No pressure, no sugarcoating. Just good information to help you make the right decision.

Connect with Rainbow Row Real Estate

Oct. 13, 2026

Waiting for a Real Estate Crash? Think About Your Next Five Years

Charleston-style porch with a stack of pennies and the message “Waiting for a Crash? Build a Plan. Think Long Term.”

Waiting for a Real Estate Crash? Think About Your Next Five Years

Who is telling you there’s an impending real estate crash—and what does that crash actually look like?

It’s a fair question.

Does it mean lower home prices? Lower mortgage rates? More homes to choose from? Sellers paying your closing costs?

Those are different things, and they don’t necessarily happen together.

Before you put your home-buying plans on hold indefinitely, it helps to understand what you’re waiting for—and how that would improve your situation.

Lower Rates Can Bring More Buyers

Lower mortgage rates can make a home more affordable by reducing the principal and interest payment on the same loan amount.

That’s good news for buyers. But you probably won’t be the only person who notices.

Some buyers who stepped back may return. Others may qualify for a purchase they couldn’t comfortably manage before.

If buyer demand grows faster than the supply of available homes, competition can increase. That can put upward pressure on prices and make sellers less willing to offer closing-cost assistance, repairs, or other incentives.

That isn’t a guaranteed outcome. More sellers may enter the market, too. The balance between supply and demand matters.

The point is that a lower rate doesn’t automatically come with a lower price and a more generous seller.

Lower Prices Help—But Look at the Whole Payment

A lower purchase price can also improve affordability. It may reduce the amount you need to borrow and the cash required for a percentage-based down payment.

But price is only one piece of the monthly-payment puzzle.

Your mortgage rate, loan amount, property taxes, insurance, mortgage insurance, and any HOA fees all help determine what a home actually costs to own.

And a significant market downturn could come with other challenges, including job uncertainty or tighter lending requirements.

A price reduction on a home you like is worth exploring. It isn’t, by itself, proof that the entire market is crashing.

For Charleston-area buyers, the useful questions are specific: What’s available in your price range? How long has it been listed? What comparable homes have sold? What terms might the seller consider?

Don’t Build Your Plan Around 2.5% Rates

Nobody can promise where mortgage rates will go next.

But counting on a return to 2.5% rates in the near future is a major assumption to build a financial decision around.

Start with a payment you can comfortably afford under today’s terms. If refinancing becomes worthwhile later, you can evaluate it then.

A future refinance should be a potential opportunity, rather than something you need to make the original purchase affordable.

The Part of Your Payment You Can Set

Rent can increase when your lease renews. It doesn’t increase every year for everyone, but future renewal pricing is something renters have to consider.

With a traditional, fully amortizing fixed-rate mortgage, the scheduled principal and interest payment stays the same over the life of the loan.

Your total housing costs can still change. Property taxes and insurance may rise. HOA dues can change. Homes need maintenance, and sometimes the air conditioner chooses the least convenient day possible to retire.

Still, knowing that your principal and interest payment is set can make long-term budgeting easier.

That predictability is a meaningful part of the homeownership conversation.

Picture Yourself Five Years From Now

Imagine it’s five years from today and people are discussing what homes and rentals cost.

You might be the slightly cheeky person saying, “We bought back in 2026.”

That doesn’t mean we can promise that a future one-bedroom apartment will cost as much as today’s three-bedroom home. Nobody knows that.

But purchasing a home with a manageable fixed payment can give you some stability while the housing market continues to change around you.

As you pay down your mortgage, you also reduce the amount you owe. If your home increases in value, that can add to your equity.

Home values can fall, too, and selling costs affect what you actually walk away with. Ownership works best when you give yourself time and financial breathing room.

And that kitchen remodel you’ve been dreaming about? Equity might eventually help make it possible. Borrowing against that equity still means taking on debt, so it deserves its own careful budget.

A Stacking-Pennies Mindset

Building financial stability is often a series of ordinary decisions.

Buying within your means. Keeping an emergency fund. Paying down principal. Maintaining your home. Giving your plan time to work.

Nothing flashy. Just stacking pennies.

Renting may be the right choice while you build savings, improve credit, or figure out where you want to live. Buying may make sense when the payment, cash requirements, and expected time in the home fit your life.

The goal is to make that decision with useful information.

Our Takeaway

If you’re waiting for a real estate crash, define what would actually make you ready to buy.

A lower payment? More savings? A particular home price? Greater job stability?

Those are things we can build a plan around.

You don’t have to predict the entire housing market to understand your own options. Let’s look at your budget, your goals, and the homes available—and see what makes sense for your next five years.

Fact-check notes: CFPB confirms the distinction between fixed principal and interest and changing taxes or insurance. NAR’s published outlook cautions buyers against betting on a return to very low rates; it does not establish a guaranteed future rate or local market outcome. The competition discussion is a conditional supply-and-demand explanation. Consumer Financial Protection Bureau

Oct. 12, 2026

Mortgage Rate Watch: Inflation Week | October 12–16, 2026

Charleston Lowcountry waterfront at sunrise with Mortgage Rate Watch and Inflation Takes Center Stage headline

Mortgage Rate Watch | October 12–16, 2026

Mortgage rates face an important inflation test this week. The bond market is closed Monday for Columbus Day, but the calendar becomes much more active beginning Wednesday with the Consumer Price Index.

Thursday then brings producer inflation, retail sales, unemployment claims and two regional manufacturing reports at the same time. Together, these releases could significantly change expectations for Federal Reserve policy and the direction of Treasury yields.

Where Mortgage Rates Stand

Freddie Mac’s latest national survey put the average 30-year fixed mortgage rate at 7.40% as of October 8, up from 7.28% the previous week. The average 15-year fixed rate was 6.73%.

These are national survey averages rather than individual quotes. A borrower’s actual rate depends on factors including credit, down payment, property type, occupancy, loan program and discount points.

The 10-year Treasury yield ended Friday near 5.24%. Mortgage rates do not follow the 10-year yield exactly, but they generally respond to many of the same forces—particularly inflation expectations and the outlook for Federal Reserve policy.

Why Inflation Matters So Much This Week

September’s employment report showed payroll growth slowing to only 29,000 jobs while unemployment increased to 4.2%. That reduced expectations for another immediate Federal Reserve rate increase.

Normally, weaker employment data would be helpful for bonds and mortgage rates. However, long-term Treasury yields and mortgage rates have remained elevated because investors are still concerned about inflation and the supply of government debt.

The Federal Reserve raised its benchmark rate by a quarter percentage point in September, bringing its target range to 3.75%–4.00%. Its next policy decision arrives October 28.

This week’s inflation reports will help markets decide whether the Fed can pause after September’s increase or whether another increase may be necessary later in the year.

Wednesday: Consumer Inflation and the Beige Book

The September Consumer Price Index will be released Wednesday at 8:30 a.m. Eastern.

Current forecasts call for headline CPI to rise approximately 0.6% for the month and 3.7% from a year earlier. Core CPI, which removes food and energy, is expected to rise approximately 0.2% for the month and 2.5% annually.

These figures are forecasts and may change before the report is released.

A softer CPI report would generally be favorable for Treasury bonds and mortgage rates. A hotter reading—particularly in core services—could push yields and mortgage pricing higher.

The Federal Reserve will release its Beige Book Wednesday afternoon. This report collects observations from businesses and other contacts across the Fed’s regional districts. Markets will look for changes in consumer spending, hiring, wages and pricing pressure.

Thursday: A Crowded Morning for the Bond Market

Thursday could be just as important as Wednesday, with several major reports arriving at 8:30 a.m. Eastern.

  • Producer Price Index
  • Retail Sales
  • Initial Jobless Claims
  • Empire State Manufacturing Index
  • Philadelphia Fed Manufacturing Index

Producer prices are expected to rise approximately 0.6% for the month, while core producer prices are expected to increase approximately 0.3%. Retail sales are forecast to grow approximately 0.4% after a strong 1.2% increase in August.

The combination matters. Hot producer inflation and strong consumer spending could suggest that price pressure remains persistent and the economy can withstand tighter monetary policy.

Softer price growth and more moderate spending would make it easier for the Fed to remain patient.

Friday: Import Prices and Industrial Production

Friday’s import-price report will show whether rising costs from energy, tariffs or overseas suppliers are feeding into the U.S. economy. Industrial production will provide another look at the strength of manufacturing, mining and utility output.

These reports are less likely to move mortgage rates than CPI or PPI, but an unexpected result could still affect the bond market.

Jared’s Take

Wednesday and Thursday are the windows I’m watching most closely. The weak September jobs report gave the Fed a reason to slow down, but cooler inflation is still needed before mortgage rates are likely to see sustained improvement. If you have a purchase or refinance in progress, it is better to discuss your rate-lock plan before the data arrives than to make a rushed decision after the market moves.

Mortgage rates can change quickly when major reports differ from expectations. The right decision depends on your loan, payment goals and timeline—not simply on trying to predict one economic headline.

Start Your Pre-Approval

Let us know if you have any questions.

Oct. 9, 2026

Are You Someone Else’s Retirement Plan?

Are You Someone Else’s Retirement Plan?

Another lease renewal shows up. You glance at the new rent, decide moving sounds like a headache, and sign for another year. It’s easy. It’s familiar. But have you stopped to ask where your own long-term plan fits into that decision?

There is nothing wrong with renting, and this is certainly not a complaint about landlords. We like landlords. We help people become landlords! Rental homes serve a real purpose, and as I like to say, there’s a butt for every seat.

You do not need to keep renewing your lease as a favor to the property owner. Your next housing decision should make sense for you.

Your Landlord Has a Plan. What Is Yours?

Rental property can be a great long-term strategy. The rent helps cover the owner’s mortgage and operating expenses. As the mortgage balance comes down, the owner can build equity. If the property grows in value, that can add to the picture too.

Of course, collecting rent is not the same as pocketing pure profit. Landlords also have repairs, insurance, property taxes, vacancies, and other expenses. But a well-managed property can produce income after those costs, and eligible, documented rental income may help an investor qualify for another purchase, depending on the loan program and lender requirements.

We fully support that plan. The question is whether you’re ready to start building something for yourself, too.

Renewing Is Easy. But Easy Deserves a Second Look.

When rent goes up at renewal, it’s tempting to absorb the increase because packing boxes and changing addresses sound worse. One more year becomes another year, and then another.

Rent does not increase by a set percentage everywhere, and buying is not automatically cheaper. But before you sign again, it may be worth comparing your actual rent with the full cost of owning a home here in the Charleston area.

That means looking beyond the mortgage payment. Property taxes, homeowners insurance, any needed flood insurance, maintenance, HOA dues, and mortgage insurance can all affect the budget. A useful conversation starts with a payment you can comfortably live with.

A Home Can Be Part of Your Retirement Plan

Homeownership gives you an opportunity to build equity as you pay down your mortgage principal. Equity is the difference between what your home is worth and what you owe against it. Appreciation can add to that equity, but home values can also fall.

Over time, that equity may give you more choices. Your first home might fit your needs today. Later, you may use some of your equity toward a different home as life changes. Eventually, downsizing may allow you to put some of the proceeds toward retirement savings or other goals.

That is an opportunity, not a guarantee. What you keep depends on your mortgage payoff, selling and moving costs, and the price of your next home. Moving into a bigger house does not automatically create more wealth, either. The purchase still has to fit your finances.

You also do not have to keep moving. Staying in a home that works for you and paying down the mortgage can be a useful long-term strategy. A paid-off home can reduce housing expenses in retirement, although taxes, insurance, and upkeep continue.

A home can be one piece of your retirement plan alongside savings and other investments. The goal is to create options for your future.

You Don’t Have to Want to Be a Landlord

You do not need a dream of owning five rentals to have a conversation about buying your first home. Maybe you just want a place of your own, room for the dog, or the ability to paint a wall without asking permission.

We can talk about your budget, credit, savings, available financing options, and how long you expect to stay. If buying makes sense now, we can map out the next steps. If it makes more sense later, we can work on a plan to get you there.

The Takeaway

Your landlord may have a great plan. You deserve one, too. Before you automatically renew for another year, let’s see whether homeownership could fit into yours. You do not have to be ready to buy tomorrow to start the conversation today.

Let’s Talk About Your Homebuying Plan